Thursday, September 09, 2010

Detecting Circular Cash Flow

Healthy doses of skepticism and due care can help uncover schemes to inflate sales.

By JOHN F. MONHEMIUS, CPA AND KEVIN P. DURKIN, CPA
DECEMBER 2009
Circular Cash Flow
Following an initial customer confirmation request with no response, a first-year auditor mails a second and third request, all under the supervision of the auditor-in-charge assigned to the account. Field work begins on the audit, but there is still no response from the customer. Another auditor scanning the cash journal from the beginning of the year through the current date notes that all outstanding invoices have subsequently been paid from this customer during this period. Customer check copies are provided, and remittances indicate that payment has been received in settlement of all outstanding invoices at fiscal year-end for this customer. But has the existence of accounts receivable from this customer at fiscal year-end really been established?
Fraudsters have been creating increasingly complex and sophisticated schemes designed to rely on potential weaknesses in the execution of audit procedures surrounding key assertions such as existence. A financial statement auditor can use his or her professional judgment while carrying out audit procedures to detect such a scheme.

IFRS for SMEs: The Next Standard for U.S. Private Companies?

By MARK FITZPATRICK, CPA and FRED FRANK, CPA
DECEMBER 2009
IFRS for SMEs
In July 2009, the International Accounting Standards Board (IASB) released International Financial Reporting Standards designed for use by small and medium-sized entities (SMEs).
IFRS for SMEs is a self-contained, standalone set of financial accounting and reporting standards. Along with the standards, the board released implementation guidance, such as example financial statements and disclosure checklists. The board is also developing training materials for IFRS for SMEs.
At approximately 230 pages, IFRS for SMEs is a simplified version of full IFRS.


More to Risk Management Than COSO ERM

By Arnold H. Schanfield, CPA, CIA, CFE
DECEMBER 2009

The authors of “ERM: Opportunities for Improvement” (Sept. 09, page 28) only discuss/reference the COSO ERM Framework.
The body of risk management knowledge includes many other sources, including lectures and books from recognized thought leaders, such as Robert Shiller, Nassim Taleb and others; at least 15 professional risk-related organizations such as the Casualty Actuarial Society, the Federation of European Risk Management Associations, the Global Association of Risk Professionals, and the Institute of Internal Auditors; and at least 15 other risk-related frameworks, including ISO 31000 and AS/NZS (Australian/New Zealand standard) 4360:2004. The authors suggest a COSO-driven risk management process without any regard for this body of knowledge. Why?
These are some of the problems with the COSO ERM Framework:

Enterprise Risk Management

NOVEMBER 2009

The Committee of Sponsoring Organizations of the Treadway Commission (COSO) published a document to help boards of directors strengthen their oversight of enterprise risks.
The four-page paper, Effective Enterprise Risk Oversight: The Role of the Board of Directors, calls attention to COSO’s Enterprise Risk Management—Integrated Framework (2004) and its definition of ERM.
In emphasizing the critical role boards of directors play in overseeing ERM, it points to the following areas discussed in COSO’s 2004 ERM framework that contribute to board risk oversight:

  • Understand the entity’s risk philosophy and concur with the entity’s risk appetite.

  • Know the extent to which management has established effective enterprise risk management of the organization.

  • Review the entity’s portfolio of risk and consider it against the entity’s risk appetite.

  • Be apprised of the most significant risks and whether management is responding appropriately.
The paper can be downloaded at coso.org.

White Paper: Understanding Internal Control and Internal Control Services

White Paper: Understanding Internal Control and Internal Control Services

By Thomas A. Ratcliffe, CPA, and Charles E. Landes, CPA
September 2009

This white paper written by Thomas A. Ratcliffe and Charles E. Landes and prepared by the AICPA Audit and Attestation Standards and Professional Publications teams seeks to clear up confusion among practitioners relating to the concept of internal control over financial reporting. It describes the concepts of internal control (specifically internal control over financial reporting) and discusses the types of services related to internal control that may be performed by practitioners in public practice.
To download the paper in PDF format, click here.


Assessing the Allowance for Doubtful Accounts

Assessing the Allowance for Doubtful Accounts

Using historical data to evaluate the estimation process

By MARK E. RILEY, CPA, PH.D. and WILLIAM R. PASEWARK, CPA, PH.D.
SEPTEMBER 2009


Friday, August 06, 2010

"Principles of Property Tax Assessment and Anti Fraud" Workshop for the Property Tax Department of the MoF-PNA

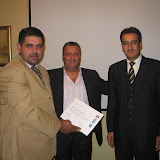
Mr. Mahmoud Nofal (middle); the Director General of the Property Tax; MoF-PNA; MR Sakher Al Ahmed, the UNDP representative (left); Dr. Mohammed Masoud ,(right), the Managing  Director of Birzeit Consulting ME. Click here to see the certificate of completion delivery / ceremony


Convergence Milestone

Revenue recognition among proposals released as FASB, IASB commit to new timeline.FASB and the IASB wrapped up the first of three rounds of issuing proposed standards in their final push toward U.S. GAAP-IFRS convergence, even as they gave themselves an extra six months to complete the ambitious project.


Wednesday, July 28, 2010

الحكم المهني للمدقق


كثيرا ما أستمع في جلسات مهنية محلية ودولية مصطلح "الحكم المهني للمدقق" عند الحديث عن أعمال التدقيق لمدقق الحسابات المستقل. وقد لاحظت في أحيان كثيرة بأن هذا المصطلح يستخدم في غير محله ، وأحيانا دون وضوح تام حول طبيعة هذا المصطلح، الغرض من إستخدامه، شروط إستخدامه وطبيعة توثيقه في أوراق العمل. بالإضافة إلى الأثر الجوهري على نوعية أعمال التدقيق والنتائج المترتبة على ذلك.

Email me for the complete article. 


Saturday, July 24, 2010

Association of Certified Fraud Examiners


The ACFE's 2010 Report to the Nations on Occupational Fraud and Abuse is based on data compiled from a study of 1,843 cases of occupational fraud that occurred worldwide between January 2008 and December 2009. All information was provided by the Certified Fraud Examiners (CFEs) who investigated those cases. The fraud cases in our study came from 106 nations — with more than 40% of cases occurring in countries outside the United States — providing a truly global view into the plague of occupational fraud.
Since the inception of the Report to the Nation more than a decade ago, we have released five updated editions — in 2002, 2004, 2006, 2008 and the current version in 2010. Like the first Report, each subsequent edition has been based on detailed case information provided by Certified Fraud Examiners (CFEs). With each new edition of the Report, we add to and modify the questions we ask of our survey participants in order to enhance the quality of the data we collect. This evolution of the Report to the Nation has enabled us to continue to draw more meaningful information from the experiences of CFEs and the frauds they encounter.
In our 2010 Report, we have, for the first time ever, widened our study to include cases from countries outside the United States. This expansion allows us to more fully explore the truly global nature of occupational fraud and provides an enhanced view into the severity and impact of these crimes. Additionally, we are able to compare the anti-fraud measures taken by organizations worldwide in order to give fraud fighters everywhere the most applicable and useful information to help them in their fraud prevention and detection efforts.
Excerpt from the Report's "Letter from the President," by James D. Ratley, CFE:
"On behalf of the ACFE, and in honor of its founder, Dr. Joseph T. Wells, CFE, CPA, I am pleased to present the 2010 Report to the Nations on Occupational Fraud and Abuse to practitioners, business and government organizations, academics, the media and the general public throughout the world. The information contained in this Report will be invaluable to those who seek to deter, detect, prevent or simply understand the global economic impact of occupational fraud."


Internal Control: The Missing Point

Unfortunately, executive management  lacks the adequate and proper understanding of the nature and importance of the internal control systems for not only the strategy formulation, but also for the strategy execution and feedback.

Does this phenomenon put the entity run by this kind of executives at risk? Definitely yes.

As any entity needs a minimum structure of  internal control systems, the absence of such systems expose the entity for too many serious business matters such as fraud and corruption.


To Whom It May Concern: Report to the Nations on Occupational FRAUD and Abuse

The Association of Certified Fraud Examiners issued lately their report titled " Report to the Nations on Occupational FRAUD and Abuse". The report is based on data compiled from a study of 1,843 cases of occupational fraud that occurred worldwide between January 2008 and December 2009.

All information was provided by Certified Fraud Examiners (CFEs) who investigated those cases. The fraud cases in the study came from 106 nations - with more than 40% of cases occuring in countries outside the United States- providing a truly global view into the plague of occupational fraud.

The report states that one-fourth of the frauds in the report caused at least $ 1 million in losses.

Though not surprising for the CFEs community, the initial detection of occupational frauds came from the following as per the 2010 Report to the Nations on Occupational FRAUD and Abuse page 16:

Tip: 40.2%
Management Review: 15.4%
Internal Audit: 13.9%
By Accident: 8.3%
Account Reconciliation: 6.1%
Document Examination: 5.2%
External Audit: 4.6%
Surveillance/ Monitoring: 2.6%
Notified by Police: 1.8%
Confession: 1%
IT Controls: 0.8%


Sunday, March 07, 2010

Three Best Ways to Catch an Employee Thief

" Employee fraud can take place right under a business owner's nose. According to the Association of Certified Fraud Examiners, an anti-fraud trade group in Austin, Texas, such activities occur on average for as long as two years before the victim organization catches on.

Here are three best ways to tell if an employee is likely to be seeking a five-finger discount:

The phone keeps ringing. Some corrupt workers will instruct friends to repeatedly call a business and ask if the owner is on site until the answer is no, says Mark R. Doyle, chief executive of Jack L. Hayes International Inc., a provider of workplace crime-prevention services in Wesley Chapel, Fla. Once they hear those "magic" words, the friend knows it's safe to come by and swipe merchandise under the rogue employee's watch, he explains.

The math doesn't add up. Two years ago, ReShonda Young noticed a subordinate at her father's transportation company, Alpha Express LLC, had turned in a weekly time sheet with more hours than he could've possibly worked. That prompted Ms. Young, a manager at the Waterloo, Iowa, company, to investigate further and she discovered that the employee had been stretching his hours for months, initially to a less-noticeable extent. "I guess it got to be a little easy," she says. Now all supervisors must review and sign workers' time cards before they can be processed, says Ms. Young.

Money problems surface. Financial pressures are a key motivator of occupational fraud, the ACFE reports. For this reason, business owners should take note of any excessive complaining by a worker about money burdens. And if such a person's lifestyle suddenly improves dramatically, this could signal he or she has their hand in the company's cookie jar."

Courtesy, WSJ March 5, 2010

Sarah E. Needleman.


How Much Does Pay Matter?

" Incentive pay is an effective tool in situations where performance can be fairly measured and where it is based largely on individual effort. But it is less effective in situations – common in today's workplace - where the measurements are highly subjective and the work is done by teams."

WSJ, March 4, 2010
Alan.Murray@wsj.com